FARM & AGRIBUSINESS INSURANCE
California Farm & Ranch Insurance
Coverage starts with understanding the way you farm.
Farm and ranch insurance can combine property and liability protection for agricultural operations. Iron Axis Insurance Agency helps California farms and ranches explore coverage based on their buildings, equipment, activities, and responsibilities to others. Each operation and coverage request needs individual review.
Insurance for the operation you run
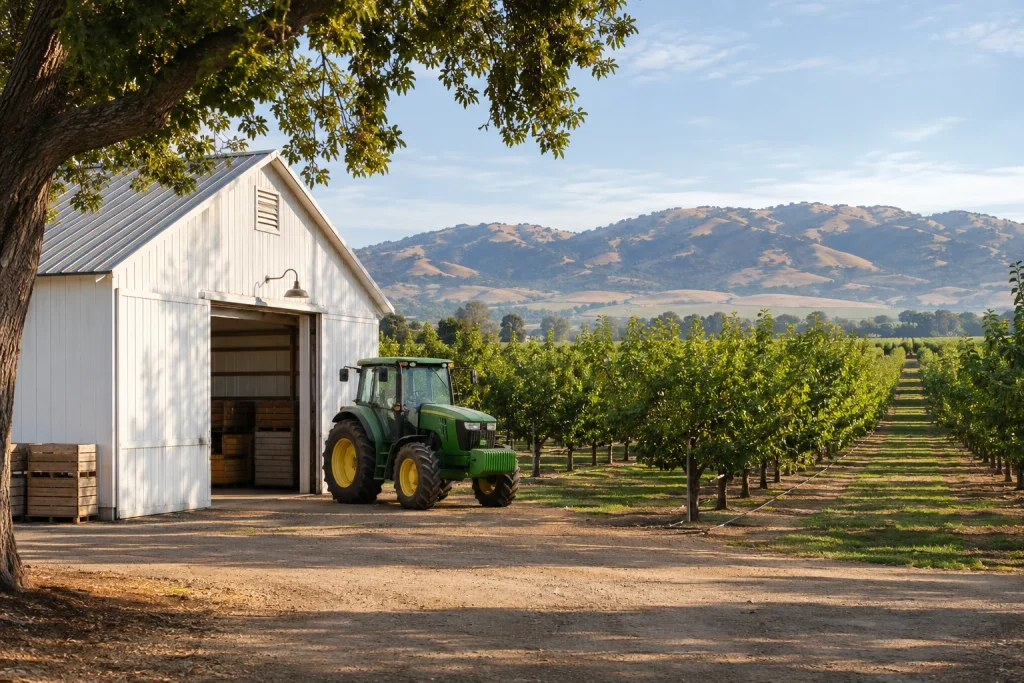
A working farm can combine a home, agricultural buildings, vehicles, employees, and several sources of income. That mix deserves a review of both the property and what happens on it. An orchard selling to a packer has different exposures from a ranch welcoming paying visitors.
Examples for eligibility review include commercial farms and ranches; fruit, vegetable, and row-crop growers; orchards and nut-growing operations; vineyards; and livestock or dairy businesses. These examples are a starting point for a conversation, not a list of guaranteed accepted operations.
What can farm and ranch insurance address?
Some protection may be available within a farm package. Other needs call for separate policies or endorsements. Review the property descriptions, covered causes of loss, limits, deductibles, and exclusions before deciding what fits.
Buildings and farm structures
Discuss barns, storage buildings, workshops, and other structures, including their use, construction, and replacement values. A residence on the farm needs its own clear review of occupancy and available coverage.
Machinery, equipment, and business property
Identify tractors, implements, tools, supplies, and other farm business personal property. Scheduling, valuation, leased equipment, off-premises use, and equipment breakdown should be discussed rather than assumed.
Premises and operational liability
Review injury and property-damage exposures arising from the farm’s activities. Public access, products sold, animals, and work away from the premises can change the protection needed.
Livestock and farm residences
Coverage for livestock or a farm dwelling may be available under particular forms or endorsements. Confirm the property insured, covered events, valuation, limits, and exclusions for each item.
Vehicles and employees
Road vehicles and employee injuries require separate attention. Vehicle ownership and use matter. California employers generally need workers’ compensation when they have employees; seasonal and part-time work should be disclosed.
Umbrella or excess liability
Additional liability limits may be available over qualifying underlying policies. Review attachment points, included policies, exclusions, and any customer contract requirements.
For general policy concepts, see the California Department of Insurance commercial insurance guide. Employer obligations are explained by the California Division of Workers’ Compensation.
Tell us about every part of the business
Public visits, tours, and U-pick activities bring people onto working agricultural premises. Farm stands and direct sales add customer and product exposures. Events and venue rentals introduce a different use of the property. Disclose these activities before relying on a policy.
Also explain custom farming, work for other farms, product processing, multiple locations, and mixed business activities. Include who performs the work, what products are handled, and whether equipment leaves your premises. A change in operations may require a change in coverage.
For events or other property uses, our event insurance information and property insurance information address separate exposures; generic business coverage should not be assumed to include farm operations.
Farm insurance and crop insurance are different
Do not assume that a farm property and liability policy covers growing crops, reduced yields, or lost crop revenue. Crop insurance is a separate subject with its own eligibility, causes of loss, reporting requirements, and deadlines. Identify crop protection as a separate need during your review.
The USDA Risk Management Agency’s specialty crop information explains available program categories. Availability of a program does not establish coverage for a particular farm or an Iron Axis appointment to that program.
What affects coverage and cost?
Insurers may consider the property location, acreage, operations, building condition, replacement values, equipment, payroll where relevant, and claims history. Requested limits, deductibles, and optional coverage also affect the review. Accurate schedules help avoid comparing quotes for different property or different limits.
Wildfire exposure can affect property eligibility, available markets, deductibles, and terms. Explain the surroundings, access, water supply, and protective measures when asked. No placement or premium can be promised before underwriting.
A straightforward review process
01 · Share the basics
Use the short quote form to describe the operation and property location. Select the coverage you need, or choose Unsure.
02 · Review the operation
The agency reviews your activities, property, liability exposures, and timing. Include any existing policy you would like to discuss during follow-up.
03 · Complete the details
Additional applications, property and equipment schedules, loss information, replacement-cost estimates, or photos may be requested through an appropriate follow-up process.
04 · Consider available options
When an insurer offers terms, review the coverage, conditions, exclusions, costs, and effective date. Options remain subject to underwriting and your acceptance of the terms.
Farm & ranch insurance FAQs
What does farm and ranch insurance cover?
Depending on the policy, a farm package may address listed buildings, equipment, business property, and liability. A dwelling, livestock, vehicles, workers’ compensation, or other needs may require separate coverage or endorsements. Review the actual policy.
Does homeowners insurance cover a working farm?
A homeowners policy may restrict or exclude business activities and farm property. Disclose agricultural operations, sales, animals, and visitors so the residence and business can be reviewed together.
Can farm insurance cover tractors and equipment?
Coverage may be available for scheduled or qualifying farm equipment. Confirm valuation, covered causes of loss, limits, deductibles, leased items, and use away from the premises.
Do visitors, farm stands, or U-pick activities require additional coverage?
They can change the liability exposure and may need specific approval or endorsements. Discuss public access, product sales, parking, hired help, and events before the activity begins.
Is crop insurance included?
Do not assume growing crops, yields, or crop revenue are included. Crop protection needs a separate, specific review of the crop, location, program, and policy.
What information is needed for a farm insurance quote?
Start with the location, operation type, contact details, requested coverage, and desired start date. The agency may follow up for acreage, building and equipment values, payroll, loss history, and supporting documents.
Can Iron Axis review an existing farm policy?
You can request a review of your current policy and operations. Discuss changes, exclusions, limits, and renewal timing. A review does not guarantee replacement coverage or a lower price.
Growing grapes? Explore our California vineyard insurance information for grape-growing, processing, and public-access distinctions.
Let’s review your farm insurance needs
Tell us how the property is used and what you want to protect. We will follow up about the information needed for an operation-specific review.
Coverage availability, eligibility, limits, deductibles, and exclusions depend on the insurer and policy. An inquiry does not bind coverage or guarantee a quote.